Buying a New Home or Condo has been gaining momentum amongst First Time Home Buyers, Rehab Property Flippers, and Buy and Hold Cash Flow Investors.
When Buying a Home or Condo, you will want to get your loan pre-qualified first. Part of getting your home loan pre-approved is showing your income and how much house you can afford.
Watch this quick video where I interview a top loan consultant to explain the process of how to show income when getting a home loan. http://www.youtube.com/watch?v=8O0PNruU4kU
To determine your maximum San Diego mortgage amount, lenders use guidelines called debt-to-income ratios. This is simply the percentage of your monthly income (before taxes) that is used to pay your monthly debts. Because there are two calculations, there is a "front" ratio and a "back" ratio and they are generally written in the following format: 33/38.
The front ratio is the percentage of your monthly income (before taxes) that is used to pay your housing costs, including principal, interest, taxes, insurance, mortgage insurance, and homeowners association fees (when applicable). The back ratio is the same thing, only it also includes your monthly consumer debt. Consumer debt can be car payments, credit card debt, installment loans, and similar related expenses. Auto or life insurance is not considered a debt.
These are just guidelines and they are flexible. If you make a larger down payment or have sterling credit, the guidelines are less rigid. The guidelines also vary according to loan program. FHA guidelines, VA guidelines, and Conventional Loan Guidelines all vary.
Whether you want to buy a high end home or a nice comfortable starter home, Oliver will be more than happy to assist you regardless of your budget.
Oliver Graf
Premium Service, Proven Results!
Showing posts with label house. Show all posts
Showing posts with label house. Show all posts


Monday
How to Buy a House Step 1 "Get Prequalified for Your Loan" - Real Estate Mortgage Prequal
When Buying a Property many people ask, what is the first step, Should I Get Pre-Qualified for a Loan first?
The answer is Definitely Yes! Before you start looking to purchase a new home or condo, you should review your finances, discuss your home loan options, figure out how much you can afford, and get pre-qualified. Getting Pre-qualified is a simple process thatwill put you in a much better position because you will have the confidence to move forward with a purchase and it will give you significantly more negotiating power when purchasing.
What does it take to get pre-qualified for your loan? Not as much as you might think... With a short phone conversation, we can briefly review information about your employment, debts, income, and assets. We can also look at your credit profile, discuss your down payment options, and cover the different loan programs that can work for you.
Once you get pre-qualified, your loan officer will give you what's called a Pre-Qualification Letter. This letter states that, as your loan officer, they have reviewed your finances and can get you qualified for a loan up to a certain amount. The whole process is simple and to the point,the paperwork is kept to a minimum, and generally your loan officer can provide most clients with a "Pre Qual letter" within about 15 minutes.
Once pre-qualified then you can go out and find the home or condo that catches your eye. Once you and you decide on "the one", being pre-qualified for your mortgage will do a couple of things. First, it lets you know in advance how much you can offer. Second, your real estate agent(me) wil submit your mortgage prequalification letter with your offer so that the seller knows that a lender has reviewed your situation and that you can afford the home.
It puts you in the best possible position and gives you the most negotiating power when buying a house, so make sure you get qualified in advance.
Contact me if you have any questions or need any help,
Oliver Graf
Real Estate Expert
http://www.ThinkOG.com
The answer is Definitely Yes! Before you start looking to purchase a new home or condo, you should review your finances, discuss your home loan options, figure out how much you can afford, and get pre-qualified. Getting Pre-qualified is a simple process thatwill put you in a much better position because you will have the confidence to move forward with a purchase and it will give you significantly more negotiating power when purchasing.
What does it take to get pre-qualified for your loan? Not as much as you might think... With a short phone conversation, we can briefly review information about your employment, debts, income, and assets. We can also look at your credit profile, discuss your down payment options, and cover the different loan programs that can work for you.
Once you get pre-qualified, your loan officer will give you what's called a Pre-Qualification Letter. This letter states that, as your loan officer, they have reviewed your finances and can get you qualified for a loan up to a certain amount. The whole process is simple and to the point,the paperwork is kept to a minimum, and generally your loan officer can provide most clients with a "Pre Qual letter" within about 15 minutes.
Once pre-qualified then you can go out and find the home or condo that catches your eye. Once you and you decide on "the one", being pre-qualified for your mortgage will do a couple of things. First, it lets you know in advance how much you can offer. Second, your real estate agent(me) wil submit your mortgage prequalification letter with your offer so that the seller knows that a lender has reviewed your situation and that you can afford the home.
It puts you in the best possible position and gives you the most negotiating power when buying a house, so make sure you get qualified in advance.
Contact me if you have any questions or need any help,
Oliver Graf
Real Estate Expert
http://www.ThinkOG.com
Friday
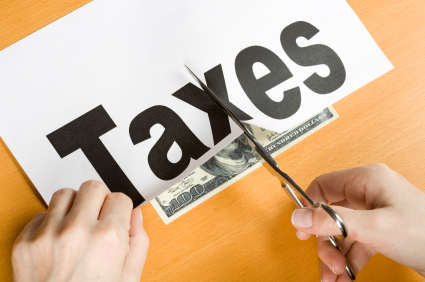
How To Lower Your Real Estate Property Taxes...
How to lower your property taxes
Despite home prices in major urban centers decreasing 31 percent between 2005 and 2009, property taxes across the U.S. increased by nearly 20 percent. There is good news, however; homeowners can fight back.
Making sense of the story
- Homeowners should keep in mind that property taxes do not always correspond with home values, because local governments typically don’t measure values every year and some have limits on annual property-tax increases.
- As a result, current property taxes might reflect the home’s value when the market was healthier. According to the Congressional Budget Office, property-tax adjustments lag behind changes in home prices by an average of three years.
Although homeowners cannot change their property-tax rate, which is set by the local government, homeowners can get their assessment lowered if they appeal to their local assessor.
One key to a successful appeal is fact checking the assessor’s work. About half of all successful appeals come from homeowners pointing out an error in the assessor’s description of the home, according to one property tax expert.
- During the appeal process, which is similar to a less-formal court hearing, homeowners may present their case to several local officials or representatives. The simplest way to convince officials that a property has been incorrectly valued is to provide evidence of the sales price of homes that are comparable to the property being discussed. This should include square footage, amenities, and neighborhood characteristics. Sale documents and photos of the property in question, as well as the comparable properties also should be brought in.
- Homeowners who have made improvements or substantial changes to the property should be cautious about appealing an assessment though, as it could have negative effects and actually increase the property’s value and, in turn, the property taxes.
From Aug 25th, 2011. C.A.R's Market Matters
Reprinted with permission of the CALIFORNIA ASSOCIATION OF REALTORS®
Contact me if you have any questions or need any help with Real Estate,
Oliver Graf
Real Estate Expert
Follow me on Twitter: Twitter.com/OliverGraf360

Thursday
Short Sale News for Homeowners: Treasury expands HAFA short sales program for vacant properties
The Treasury department recently announced several changes to the Home Affordable Foreclosure Alternatives (HAFA) program to make the program accessible to more borrowers and properties. With the lackluster numbers on permanent HAMP modifications and other widely reported problems, HAFA and short sales may become a bigger focus for policy makers, loan servicers, and REALTORS® in 2011.
One particularly notable change announced relates to HAFA eligibility of vacant properties. Previously, only properties which were vacant for 90 days due to employment-related moves of more than 100 miles were typically eligible. Under the new HAFA guidelines, previously owner-occupied properties which have been vacant or rented for up to 12 months are eligible as long as, among other things, the seller has not purchased another property in the interim.
The new guidelines are effective Feb. 1, 2011, and are not applicable for, among others, loans owned or guaranteed by government owned or sponsored entities including Fannie Mae, Freddie Mac, FHA and VA.
From January 26th, 2011. Market Matters Weekly Advisory
Reprinted with permission of the CALIFORNIA ASSOCIATION OF REALTORS®
Contact me if you have any questions or need any help,
Oliver Graf
Real Estate Expert
Follow me on Twitter: Twitter.com/OliverGraf360
One particularly notable change announced relates to HAFA eligibility of vacant properties. Previously, only properties which were vacant for 90 days due to employment-related moves of more than 100 miles were typically eligible. Under the new HAFA guidelines, previously owner-occupied properties which have been vacant or rented for up to 12 months are eligible as long as, among other things, the seller has not purchased another property in the interim.
The new guidelines are effective Feb. 1, 2011, and are not applicable for, among others, loans owned or guaranteed by government owned or sponsored entities including Fannie Mae, Freddie Mac, FHA and VA.
From January 26th, 2011. Market Matters Weekly Advisory
Reprinted with permission of the CALIFORNIA ASSOCIATION OF REALTORS®
Contact me if you have any questions or need any help,
Oliver Graf
Real Estate Expert
Follow me on Twitter: Twitter.com/OliverGraf360
Tuesday
Understanding the Real Estate Foreclosure Process (3 Steps)
In this market, housing values are declining as unemployment is increasing. For a homeowner, that means that the value of the house will be “upside-down”, and the market value of the home is actually less than the loan amount. Due to high unemployment we have seen a rise of foreclosures, where the bank takes back the property.
Foreclosure is the proceeding in which a bank or other secured creditor sells or repossesses a real property after the Homeowner has failed to comply with an agreement between the lender and the borrower (a mortgage or a deed of trust).
This happens when a property owner stops making their mortgage payments. After consistently missing payments the lender will usually consider the loan in default and begin with the foreclosure proceedings. The Lender at this point has the right to sell the property or even call the loan due.
All short sale / foreclosures have 3 steps in the timeline towards the property being sold.
1. Notice of Default (NOD):
A Notice of Default is a public notice given to the homeowner. In some states the notice is posted on the window or door. When a borrower is in default, or behind in mortgage payments, the lender will seize the home. In California lenders usually do not file an NOD until the homeowner is at least 90 days behind in payments.
2. Notice of Trustee Sale (NOTS):
A Notice of Trustee Sale is a public notice, published in a newspaper communicating a date for auction. This is also generally posted on the door; it will be a minimum of 21 days before the sale takes place.
3. Auction:
An auction is a public place where properties are auctioned to the highest bidder.
To your success,
Oliver Graf
Real Estate Expert

Friday
How to Price a Property correctly - Sell Real Estate FAST
How to Price a Property correctly so you can sell it quick and get the most amount of money - Sell Real Estate FAST
When you put a property up for sale, the price you set is the most critical factor in terms of the return you’ll receive on your investment. That’s why you should always get a professional evaluation before deciding the price (You can contact me anytime if you would like a FREE help pricing property). Look at the facts and do an honest assessment of the property, based on several factors, including but not limited to:
• Market conditions
• Condition of your home
• Repairs or improvements
• Selling timeframe
In real estate terms, “market value” is the price at which a particular house, in its current condition, should sell within 30 to 90 days.
If the price of your property is too high, this could cause several things:
• Limits buyers visiting the property. Potential buyers may not view the home because it appears to be out of their buying range or “over priced”.
• Limits the number showings. Other salespeople may be more reluctant to view your home and show it to their prospective buyers.
• Used as leverage against you. Other Realtors® may use the price of the subject property to drive the sale of other homes that are more competitively priced.
• Longer time on the market. When a home is on the market too long, it may be perceived as “stale” or defective. Buyers wonder, “what’s wrong with the property,” or “why hasn’t this sold yet?”
• Lower price. An home that is priced too high, still on the market beyond the average selling time, could lead to a lower selling price in the end. To sell it, you will have to reduce the price – sometimes more than once. In the end, you run the risk of getting less than if it had been properly priced in the first place.
• Wasted time and energy. A bank appraisal is most often required to finance a home, so if it is overpriced it will not appraise and they buyers lender will force a reduced price.
Real Estate Professionals have known it for years – well-kept homes that are priced right from the start get you the fastest sale for the best price! And that’s why you need a highly trained professional to assist you in the selling of your home.
Often, in a seller’s market, homes that are priced slightly below market value initially will sell for more, simply because of the extra interest they incite. This can be a risk, however, and when it comes to such a decision you can contact me for help any time.
If you have any other questions please contact me anytime
Oliver Graf
Real Estate Expert
****** Make sure you sign up for our FREE mailing list today! *****
--
Real Estate Sales
Real Estate Buying
Real Estate Purchase
San Diego Based Real Estate Blog
When you put a property up for sale, the price you set is the most critical factor in terms of the return you’ll receive on your investment. That’s why you should always get a professional evaluation before deciding the price (You can contact me anytime if you would like a FREE help pricing property). Look at the facts and do an honest assessment of the property, based on several factors, including but not limited to:

• Market conditions
• Condition of your home
• Repairs or improvements
• Selling timeframe
In real estate terms, “market value” is the price at which a particular house, in its current condition, should sell within 30 to 90 days.
If the price of your property is too high, this could cause several things:
• Limits buyers visiting the property. Potential buyers may not view the home because it appears to be out of their buying range or “over priced”.
• Limits the number showings. Other salespeople may be more reluctant to view your home and show it to their prospective buyers.
• Used as leverage against you. Other Realtors® may use the price of the subject property to drive the sale of other homes that are more competitively priced.
• Longer time on the market. When a home is on the market too long, it may be perceived as “stale” or defective. Buyers wonder, “what’s wrong with the property,” or “why hasn’t this sold yet?”
• Lower price. An home that is priced too high, still on the market beyond the average selling time, could lead to a lower selling price in the end. To sell it, you will have to reduce the price – sometimes more than once. In the end, you run the risk of getting less than if it had been properly priced in the first place.
• Wasted time and energy. A bank appraisal is most often required to finance a home, so if it is overpriced it will not appraise and they buyers lender will force a reduced price.
Real Estate Professionals have known it for years – well-kept homes that are priced right from the start get you the fastest sale for the best price! And that’s why you need a highly trained professional to assist you in the selling of your home.
Often, in a seller’s market, homes that are priced slightly below market value initially will sell for more, simply because of the extra interest they incite. This can be a risk, however, and when it comes to such a decision you can contact me for help any time.
If you have any other questions please contact me anytime
Oliver Graf
Real Estate Expert
****** Make sure you sign up for our FREE mailing list today! *****
--
Real Estate Sales
Real Estate Buying
Real Estate Purchase
San Diego Based Real Estate Blog

Tuesday
How to Successfully Launch a profitable Real Estate Business
 How to Successfully Launch a profitable Real Estate Business
The hardest part of getting your Real Estate Investing business started is overcoming the fear of the unknown that comes with attempting anything new. Many of my students get stuck before they even start suffering from analysis paralysis. Getting caught in the train of thought that if they just buy one more seminar, they will finally feel confident enough to get in the game and finally start doing deals.
What we all need to understand is that fear will never go away no matter how many courses you buy, or how many boot-camps and seminars you attend. The only way to get over this fear is by actually getting in the game, you need to face your fears and execute! We do not need to start with huge deals getting started, or even any of our own money. So many times, investors think that they need to put everything on the line to get into real estate investing. That is so far from the truth, I did my first almost 50 deals without ever using any of my own money or credit. This are what everyone has heard of called "baby steps", everyone that is successful today started with baby steps. These are just stepping stones to growing a big investing operation like myself and my partners have. It all started with finally pulling the trigger and doing are first deal. Looking back on it now with over 300 deals under my belt, the only regret I have is not getting started sooner!
Here is an easy action guide for you to start using today, this will help you finally start working towards your goals. Follow these easy steps and you will be well on your way to being a successful real estate investor!
Attend a REIA / Meetup / Investment club meetings : Networking with other investors is the best and first step to starting your investing career. The people you will meet at these events can be a big help to you while first getting started. I always say that "Relationships are the only shortcuts to success". For a lot of us this can seem a little nerve wrecking in the beginning, but be rest assured that this is the most important step in starting your business. Another major bonus is that these meeting are usually free! If this is a big challenge to overcome, you might want to consider attending one of my events to help you sharpen your networking skills. Remember... you are always on the air!
Meet with successful Investors: Sometimes we need to see before we can believe. Meeting with an active successful investor will give you the inspiration you need to get your butt into gear. When I was first getting started I made it a point to meet and surround myself with as many of these people as I could. We have all heard that saying..."You income is the exact average of the 5 people you hang out with most"...so why are you hanging out with your broke friends? If you need help finding successful investors to meet with, a REIA or Networking group as explained above is a great place to start.
Take Action: The only way to invest in your first deal is by finding your first deal!! Whatever your chosen model is, you need to find properties to invest in. So if you are going to be looking for motivated sellers, then you need to get on the phone with sellers. The only way we can get better at talking to our clients is by talking to more and more of them. Practice makes perfect, right? No! Perfect practice makes perfect! Practice your scripts, roll play your scripts and get on the PHONE!! Read this very carefully...TAKING ACTION WILL MAKE YOU RICH!!
Getting starting and making money investing in real estate is not easy and anyone that tells you it is has not done any deals. If you want to be successful you need to be ready to get outside of your comfort zone and act in spite of fear! Because of this we must make sure we are always surrounding ourselves with the right people on a regular basis as well as feeding our mind positive thoughts on a regular basis. Make sure to check back for my next post on "The Winning Mindset."
What are you going to do to get started?
Yours in Success,
Sam Khorramian
Success Expert
****** Make sure you sign up for our FREE mailing list today! *****
Real Estate Buying
Real Estate Investing
Real Estate Tips and Tricks
San Diego Based Real Estate Blog

Monday
10 Reasons Professional Investors and Real Estate Agents might want to consider outsourcing their Short Sales

With statistics now showing that 1 in 4 mortgages in the United States are upside down, there is no shortage of short sale business to be found. The question is what are you doing with them? Here are some thoughts to consider on whether to outsource the negotiations or try and negotiate yourself....
1) You have to have a Buyer to start the Short Sale process with the Lender. They will not even look at your package without an offer.
2) Short Sales can take a very long time to negotiate. You risk losing buyers because people want to buy NOW!
3) Short Sales can take a lot of time and effort. As a successful Real Estate Agent, you have better things to do than negotiating with the banks, you should be focused on listing and market properties, finding sellers, and finding buyers.
4) There are some states states where attempting to work a short sale for a homeowner can be looked at as breaking the law because you are “acting as a lawyer.”
5) The Lender will battle you on all aspects of your offer, including the commission. You must be prepared to fight the lender for what you are worth
6) You’re a professional Real Estate Agent, not a professional loss mitigator. Good negotiators have years of experience in the loss mitigation departments and understand how the loss mitigation process works.
7) Working with a negotiation company can benefit you because they have developed relationships with the Lenders that can expedite the Short Sale negotiation process.
8) A Short Sale requires stacks and stacks of extra paperwork that is outside of the normal forms you may be used to. Partnering with a loss mitigation team can help you because they already know the items each Lender requires and can provide them to the lender ahead of time to shorten the Short Sale process.
9) Meeting the BPO agent. Most good short sale negotiation companies will send someone out to meet the BPO agent so you can spend your time on more important things.
10) Short Sales will take your focus from the things you know you need to do in order to be a successful Real Estate Agent and have you working on tedious time consuming tasks. In my opinion its better to hand it over to someone else who has the experience doing the negotiations and focus on getting more business!!!
What has been you biggest challenge with short sales?
Contact me if you would like help finding a company to outsource your short sale negotiations too.
To your success,
Oliver Graf
Real Estate Expert
*** Make sure you sign up for our FREE mailing list today! ***
--
Real Estate Submit Short Sale
Real Estate Short Sale
Real Estate Short Sale Tips
San Diego Based Real Estate Blog

Tuesday
16 Tips to bring you Massive Success
16 Tips to bring you Massive Success

1. Get and stay out of your comfort zone.
I believe that not much happens of any significance when we're in our comfort zone. When you are out of your comfort zone or uncomfortable, you are growing.
2. Never give up.
Almost nothing works the first time it's attempted. Just because what you're doing does not seem to be working, doesn't mean it won't work. It just means that it might not work the way you're doing it. If it was easy, everyone would be doing it!
3. When you're ready to quit, you're closer than you think.
There's an old Chinese saying that I just love, and I believe it is so true. It goes like this: "The temptation to quit will be greatest just before you are about to succeed." Most people quit when they are 3 feet from GOLD!!
4. With regard to whatever worries you, not only accept the worst thing that could happen, but make it a point to quantify what the worst thing could be.
Very seldom will the worst consequence be anywhere near as bad as a cloud of "undefined consequences." During the toughest times in my business when I felt like nothing was working I would just think to myself “This can’t kill me, one day I’ll look back on this and laugh!” Hahaha…
5. Focus on what you want to have happen.
Remember that old saying, "Whether you think you will or not, you are right." It is always so important to keep a positive mindset. 80% of your success will come from this.
6. Take things a day at a time.
No matter how difficult your situation is, you can get through it if you don't look too far into the future, and focus on the present moment. You can get through anything one day at a time. “This too will pass”
7. Always be moving forward.
Never stop investing. Never stop improving. Never stop doing learning. The moment you stop improving your organization, it starts to die. Make it your goal to be better each and every day, in some small way. Remember the Japanese concept of Kaizen. Small daily improvements eventually result in huge advantages.
8. Measure everything of significance.
I swear this is true. Anything that is measured and watched, improves. Keep track of your numbers. Hold yourself accountable and watch your business grow.
9. Anything that is not managed will deteriorate.
If you want to uncover problems you don't know about, take a few moments and look closely at the areas you haven't examined for a while. I guarantee you problems will be there.
10. Pay attention to your competitors, but pay more attention to what you're doing.
When you look at your competitors, remember that everything looks perfect at a distance.
What is your edge? What make you different? Why should someone work with you over the competition?
11. Never let anybody push you around.
Never let someone tell you “It can’t be done.” Don’t let other people’s opinion determine your success.
12. Never expect life to be fair.
Life isn't fair. You make your own breaks. Don’t let your down falls hold you back. You will fail many times before you succeed. Fail Forward Faster!!
13. Solve your own problems.
You'll find that by coming up with your own solutions, you'll develop a competitive edge. Masura Ibuka, the co-founder of SONY, said it best: "You never succeed in technology, business, or anything by following the others." Be you, and YOU will succeed!
14. Don't take yourself too seriously.
Lighten up. If you are walking around upset and uptight that is what you will get more of. Be happy and positive! None of us are in control as much as we like to think we are.
15. There's always a reason to smile.
Find it. After all, you're really lucky just to be alive. Life is short. Remember: "We're not here for a long time, we're here for a good time!"
16. Money is how business people keep score!
What’s your score?
To your success,
Sam Khorramian
Success Expert
*** Make sure you sign up for our FREE mailing list today! ***
.

Monday
How to get more Short Sale Business Tip #2 of 8 (For Investors, Realtors, and Brokers)
How to get more Short Sale Business Tip #2 of 8 (For Investors, Realtors, and Brokers)
 Tip #2 of 8 on how to get more Short Sale Business
I am committed to helping Realtors and Brokers expand
their business by providing marketing tips and structuring
the short sale experience so you keep your full
commission and do minimal work.
This tip is all about:
CALLING LOAN MODIFICATION COMPANIES TO GET TURN DOWNS
This is an excellent way to generate
short sale listings! Many homeowners want to
explore a loan modification before resorting
to a short sale, however most simply
do not qualify. Mainly because they have a
permanent hardship (like loss of job)or they
can't afford the three grand that the loan
mod company charges.
Most Loan Modification companies have
large quantities of these "bad" leads (bad for them, good for you).
Partnering with just one large company could staff a
full office of agents listing short sales for months!
The idea is that you call them and set up a relationship
where both you and the loan mod company are
benefiting. If you call and simply try to ask
for business you might not get very far, but if
you get creative and come up with a plan
where everyone will benefit from the relationship
you can have great success!
Now is the time to make those partnerships
happen and then sit back and watch the short sale
listings come to you.
Keep in mind, with Short Sale Pros you keep
all your commission and we do all the work work with the bank!
What other methods are you using to take advantage of the short sale market? Look out of tip 3 coming out soon!
Keep in mind, you can contact me anytime to help get your short sales closed, with our model you keep all your commission and do none of the work!
To your success,
Oliver Graf
Real Estate Expert
Follow me on Twitter: Twitter.com/OliverGraf360
*** Make sure you sign up for our FREE mailing list today! ***
--
Real Estate Foreclosure
Real Estate Short Sale
Real Estate Avoid Foreclosure
San Diego Based Real Estate Blog

Subscribe to:
Posts (Atom)


 Posts